SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
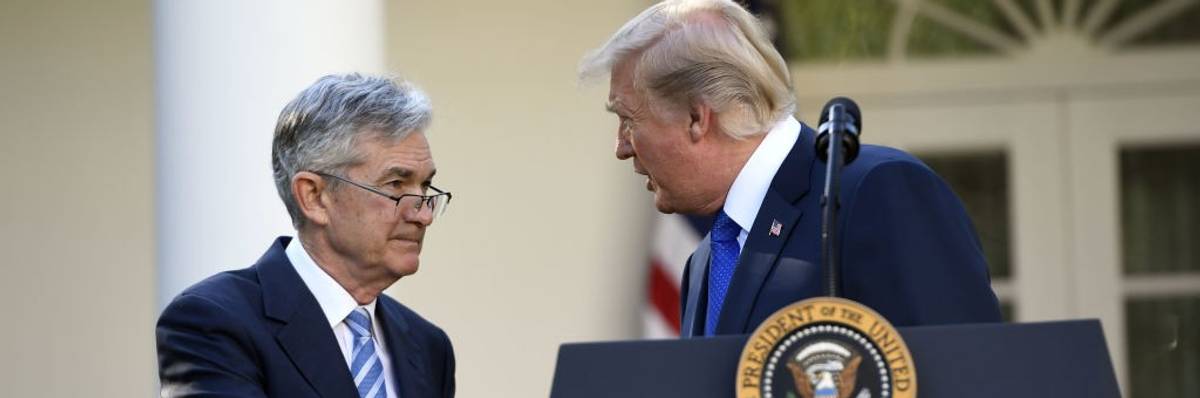
U.S.President Donald Trump shakes hands as he announces his nominee for Chairman of the Federal Reserve, Jerome Powell, in the Rose Garden of the White House in Washington, DC, November 2, 2017.
And yes, this is definitely a bailout. What happened in 2018 was effectively allowing SVB and other banks to still benefit from insurance without having to pay for it.
There are two key points that people should recognize about the decision to guarantee all the deposits at Silicon Valley Bank (SVB):
The first point is straightforward. We gave a government guarantee of great value to people who had not paid for it.
We will get a lot of silly game playing on this issue, just like we did back in 2008-09. The game players will tell us that this guarantee didn’t cost the government a penny, which will very likely end up being true. But that doesn’t mean we didn’t give the bank’s large depositors something of great value.
If the government offers to guarantee a loan, it makes it far more likely that the beneficiary will be able to get the loan and that they will pay a lower interest rate for this loan. In this case, the people who held large uninsured deposits at SVB apparently decided that it was better, for whatever reason, to expose themselves to the risk by keeping these deposits at SVB, rather than adjusting their finances in a way that would have kept their money better protected.
This would have meant either parking their deposits at a larger bank that was subject to more careful scrutiny by regulators, or adjusting their assets so that they were not so exposed to a single bank. They also could have taken ten minutes to examine SVB’s financial situation, which was mostly a matter of public record.
For whatever reason, the bank’s large depositors chose to expose themselves to serious risk. When their bet turned out badly, they in effect wanted the government to provide the insurance that they did not pay for.
This brings us to the second point; this is Donald Trump’s bailout. The reason this is a bailout is that the government is providing a benefit that the depositors did not pay for. It also is, in effect, a subsidy to other mid-sized banks, since it tells their depositors that they can count on the government covering their deposits, even though they are not insured and the bank is not subject to the same scrutiny as the largest banks.
This is where the fault lies with Donald Trump. It was his decision to stop scrutinizing banks with assets between $50 billion and $250 billion that led to the problems at SVB.
Prior to the passage of this bill, a bank the size of SVB would have been subject to regular stress tests. A stress test means projecting how a bank would fare in various bad situations, like the rise in interest rates that apparently sank SVB.
If regulators had subjected to SVB to a stress test, they would have almost surely recognized its problems. They then would have required it to raise more capital and/or shed deposits.
But Trump pulled the regulators off the job. This is wrongly described as “deregulation.” It isn’t.
Deregulation would mean both eliminating the scrutiny of SVB and ending insurance for the bank. (In principle that would mean ending all deposit insurance, not the just the insurance for large accounts that is at issue here.)
What happened in 2018 was effectively allowing SVB to still benefit from insurance without having to pay for it. It is comparable to telling drivers that they don’t have to buy auto insurance, but will still be covered if they are in an accident. Or, perhaps a better example would be telling a restaurant that it is covered by fire insurance, but it doesn’t have to adhere to safety standards.
It is dishonest to describe this as “deregulation.” It is the government giving a subsidy to the banks in question. It is understandable that the banks prefer to describe their subsidy as deregulation, but it is not accurate.
Anyhow, this bailout is the Donald Trump bailout. He touted the 2018 bill when he signed it. We are now seeing the fruits of his action.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
There are two key points that people should recognize about the decision to guarantee all the deposits at Silicon Valley Bank (SVB):
The first point is straightforward. We gave a government guarantee of great value to people who had not paid for it.
We will get a lot of silly game playing on this issue, just like we did back in 2008-09. The game players will tell us that this guarantee didn’t cost the government a penny, which will very likely end up being true. But that doesn’t mean we didn’t give the bank’s large depositors something of great value.
If the government offers to guarantee a loan, it makes it far more likely that the beneficiary will be able to get the loan and that they will pay a lower interest rate for this loan. In this case, the people who held large uninsured deposits at SVB apparently decided that it was better, for whatever reason, to expose themselves to the risk by keeping these deposits at SVB, rather than adjusting their finances in a way that would have kept their money better protected.
This would have meant either parking their deposits at a larger bank that was subject to more careful scrutiny by regulators, or adjusting their assets so that they were not so exposed to a single bank. They also could have taken ten minutes to examine SVB’s financial situation, which was mostly a matter of public record.
For whatever reason, the bank’s large depositors chose to expose themselves to serious risk. When their bet turned out badly, they in effect wanted the government to provide the insurance that they did not pay for.
This brings us to the second point; this is Donald Trump’s bailout. The reason this is a bailout is that the government is providing a benefit that the depositors did not pay for. It also is, in effect, a subsidy to other mid-sized banks, since it tells their depositors that they can count on the government covering their deposits, even though they are not insured and the bank is not subject to the same scrutiny as the largest banks.
This is where the fault lies with Donald Trump. It was his decision to stop scrutinizing banks with assets between $50 billion and $250 billion that led to the problems at SVB.
Prior to the passage of this bill, a bank the size of SVB would have been subject to regular stress tests. A stress test means projecting how a bank would fare in various bad situations, like the rise in interest rates that apparently sank SVB.
If regulators had subjected to SVB to a stress test, they would have almost surely recognized its problems. They then would have required it to raise more capital and/or shed deposits.
But Trump pulled the regulators off the job. This is wrongly described as “deregulation.” It isn’t.
Deregulation would mean both eliminating the scrutiny of SVB and ending insurance for the bank. (In principle that would mean ending all deposit insurance, not the just the insurance for large accounts that is at issue here.)
What happened in 2018 was effectively allowing SVB to still benefit from insurance without having to pay for it. It is comparable to telling drivers that they don’t have to buy auto insurance, but will still be covered if they are in an accident. Or, perhaps a better example would be telling a restaurant that it is covered by fire insurance, but it doesn’t have to adhere to safety standards.
It is dishonest to describe this as “deregulation.” It is the government giving a subsidy to the banks in question. It is understandable that the banks prefer to describe their subsidy as deregulation, but it is not accurate.
Anyhow, this bailout is the Donald Trump bailout. He touted the 2018 bill when he signed it. We are now seeing the fruits of his action.
There are two key points that people should recognize about the decision to guarantee all the deposits at Silicon Valley Bank (SVB):
The first point is straightforward. We gave a government guarantee of great value to people who had not paid for it.
We will get a lot of silly game playing on this issue, just like we did back in 2008-09. The game players will tell us that this guarantee didn’t cost the government a penny, which will very likely end up being true. But that doesn’t mean we didn’t give the bank’s large depositors something of great value.
If the government offers to guarantee a loan, it makes it far more likely that the beneficiary will be able to get the loan and that they will pay a lower interest rate for this loan. In this case, the people who held large uninsured deposits at SVB apparently decided that it was better, for whatever reason, to expose themselves to the risk by keeping these deposits at SVB, rather than adjusting their finances in a way that would have kept their money better protected.
This would have meant either parking their deposits at a larger bank that was subject to more careful scrutiny by regulators, or adjusting their assets so that they were not so exposed to a single bank. They also could have taken ten minutes to examine SVB’s financial situation, which was mostly a matter of public record.
For whatever reason, the bank’s large depositors chose to expose themselves to serious risk. When their bet turned out badly, they in effect wanted the government to provide the insurance that they did not pay for.
This brings us to the second point; this is Donald Trump’s bailout. The reason this is a bailout is that the government is providing a benefit that the depositors did not pay for. It also is, in effect, a subsidy to other mid-sized banks, since it tells their depositors that they can count on the government covering their deposits, even though they are not insured and the bank is not subject to the same scrutiny as the largest banks.
This is where the fault lies with Donald Trump. It was his decision to stop scrutinizing banks with assets between $50 billion and $250 billion that led to the problems at SVB.
Prior to the passage of this bill, a bank the size of SVB would have been subject to regular stress tests. A stress test means projecting how a bank would fare in various bad situations, like the rise in interest rates that apparently sank SVB.
If regulators had subjected to SVB to a stress test, they would have almost surely recognized its problems. They then would have required it to raise more capital and/or shed deposits.
But Trump pulled the regulators off the job. This is wrongly described as “deregulation.” It isn’t.
Deregulation would mean both eliminating the scrutiny of SVB and ending insurance for the bank. (In principle that would mean ending all deposit insurance, not the just the insurance for large accounts that is at issue here.)
What happened in 2018 was effectively allowing SVB to still benefit from insurance without having to pay for it. It is comparable to telling drivers that they don’t have to buy auto insurance, but will still be covered if they are in an accident. Or, perhaps a better example would be telling a restaurant that it is covered by fire insurance, but it doesn’t have to adhere to safety standards.
It is dishonest to describe this as “deregulation.” It is the government giving a subsidy to the banks in question. It is understandable that the banks prefer to describe their subsidy as deregulation, but it is not accurate.
Anyhow, this bailout is the Donald Trump bailout. He touted the 2018 bill when he signed it. We are now seeing the fruits of his action.