SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Corporate America's relentless year-long lobbying campaign partially paid off this past weekend when Senate Democrats--constrained by two industry-allied lawmakers in their own party and united GOP opposition--approved legislation that stands as a mere shadow of its predecessor, the Build Back Better Act.
Big business is particularly pleased that it was able to fend off Democrats' push to increase the corporate tax rate and impose other levies on the ultra-rich and private equity firms, which exploit glaring loopholes to systematically avoid taxation.
"Tax-dodging multinational corporations are still able to play games with their operational and accounting practices."
Neil Bradley, chief policy officer at the U.S. Chamber of Commerce--the largest and most influential corporate lobbying group in the country--openly expressed relief Monday at the extent to which the Inflation Reduction Act was scaled back compared to the most ambitious version of Build Back Better, a package that would have partially reversed the 2017 GOP tax cuts.
"If 2017's tax reforms were a 10 and Build Back Better was a zero, where is this? I guess I'd say it's a five," Bradly said of the Inflation Reduction Act in an interview with the Financial Times. "It didn't cut taxes; it raised taxes, but it's a lot better than Build Back Better."
The Chamber was one of a number of powerful business groups that lobbied aggressively against Build Back Better and elements of the Inflation Reduction Act, the original version of which included a provision targeting the notorious carried interest loophole as well as a 15% minimum tax on corporations with more than $1 billion in annual profits.
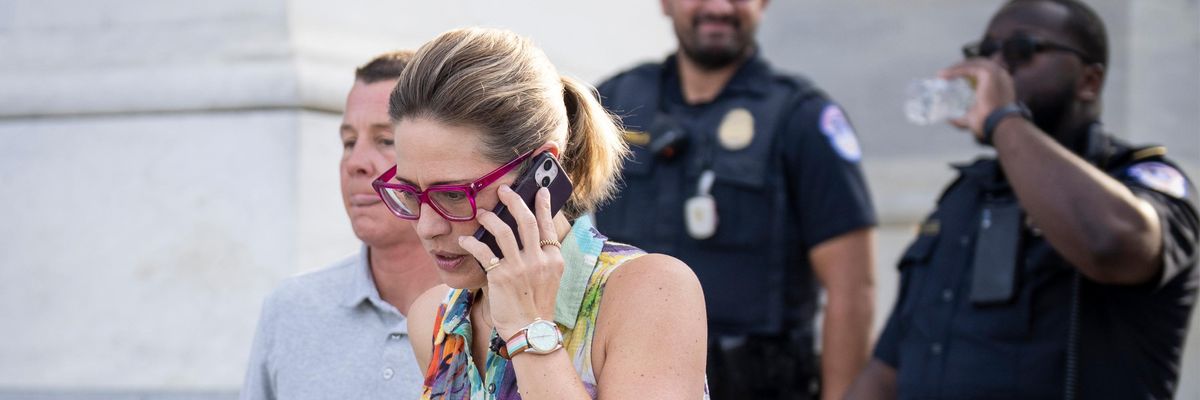
But thanks to a last-minute intervention by Sen. Kyrsten Sinema (D-Ariz.)--a reliable ally of corporate interests--the carried interest proposal was scrapped entirely while the corporate minimum tax was watered down with a carveout for private equity, which helps bankroll the Arizona Democrat's campaigns.
Senate Democrats opted to replace the carried interest provision with a 1% excise tax on stock buybacks, drawing wails of complaint from corporate lobbying organizations including the Chamber.
As the New York Times reported Monday, the proposed corporate minimum tax "had already been whittled down before the changes over the weekend" due to Sinema, who "pushed last week to preserve deductions that manufacturers use to offset the cost of equipment purchases."
Additionally, the Times noted, "lawmakers decided to keep a deduction for wireless spectrum purchases that telecommunications companies said was important for the rollout of high-speed broadband."
The National Association of Manufacturers, a corporate lobbying group that targeted Sinema with a late-stage flurry of ads opposing the minimum tax, voiced appreciation that "the 'book tax' has been revised to reflect the importance of job-creating investments in machinery and equipment."
The organization still expressed opposition to the Inflation Reduction Act as a whole, claiming the "new taxes will still deliver a blow to our industry's ability to raise wages, hire workers, and invest in our communities."
Related Content

While advocates of progressive tax policy largely praised the Inflation Reduction Act as a step in the right direction, they expressed concern that the bill doesn't go nearly far enough to cut off tax dodging by large companies--a critique vindicated by the bill's partly favorable reception in some segments of corporate America.
"Left out of the Inflation Reduction Act were key fixes to the U.S. international tax code that would more definitively remove the incentive for large multinationals to shift profits offshore or erode the U.S. tax base," the Financial Accountability and Corporate Transparency (FACT) Coalition pointed out in a press release on Monday.
Ryan Gurule, policy director at the FACT Coalition, said that "this bill cannot be the final chapter in the fight against profit-shifting and offshoring practices by large corporations."
"There is still too much vital revenue on the line," added Gurule, "as tax-dodging multinational corporations are still able to play games with their operational and accounting practices to shift hundreds of billions of dollars in profits each year to secretive tax havens."
Corporate America's relentless year-long lobbying campaign partially paid off this past weekend when Senate Democrats--constrained by two industry-allied lawmakers in their own party and united GOP opposition--approved legislation that stands as a mere shadow of its predecessor, the Build Back Better Act.
Big business is particularly pleased that it was able to fend off Democrats' push to increase the corporate tax rate and impose other levies on the ultra-rich and private equity firms, which exploit glaring loopholes to systematically avoid taxation.
"Tax-dodging multinational corporations are still able to play games with their operational and accounting practices."
Neil Bradley, chief policy officer at the U.S. Chamber of Commerce--the largest and most influential corporate lobbying group in the country--openly expressed relief Monday at the extent to which the Inflation Reduction Act was scaled back compared to the most ambitious version of Build Back Better, a package that would have partially reversed the 2017 GOP tax cuts.
"If 2017's tax reforms were a 10 and Build Back Better was a zero, where is this? I guess I'd say it's a five," Bradly said of the Inflation Reduction Act in an interview with the Financial Times. "It didn't cut taxes; it raised taxes, but it's a lot better than Build Back Better."
The Chamber was one of a number of powerful business groups that lobbied aggressively against Build Back Better and elements of the Inflation Reduction Act, the original version of which included a provision targeting the notorious carried interest loophole as well as a 15% minimum tax on corporations with more than $1 billion in annual profits.
But thanks to a last-minute intervention by Sen. Kyrsten Sinema (D-Ariz.)--a reliable ally of corporate interests--the carried interest proposal was scrapped entirely while the corporate minimum tax was watered down with a carveout for private equity, which helps bankroll the Arizona Democrat's campaigns.
Senate Democrats opted to replace the carried interest provision with a 1% excise tax on stock buybacks, drawing wails of complaint from corporate lobbying organizations including the Chamber.
As the New York Times reported Monday, the proposed corporate minimum tax "had already been whittled down before the changes over the weekend" due to Sinema, who "pushed last week to preserve deductions that manufacturers use to offset the cost of equipment purchases."
Additionally, the Times noted, "lawmakers decided to keep a deduction for wireless spectrum purchases that telecommunications companies said was important for the rollout of high-speed broadband."
The National Association of Manufacturers, a corporate lobbying group that targeted Sinema with a late-stage flurry of ads opposing the minimum tax, voiced appreciation that "the 'book tax' has been revised to reflect the importance of job-creating investments in machinery and equipment."
The organization still expressed opposition to the Inflation Reduction Act as a whole, claiming the "new taxes will still deliver a blow to our industry's ability to raise wages, hire workers, and invest in our communities."
Related Content
While advocates of progressive tax policy largely praised the Inflation Reduction Act as a step in the right direction, they expressed concern that the bill doesn't go nearly far enough to cut off tax dodging by large companies--a critique vindicated by the bill's partly favorable reception in some segments of corporate America.
"Left out of the Inflation Reduction Act were key fixes to the U.S. international tax code that would more definitively remove the incentive for large multinationals to shift profits offshore or erode the U.S. tax base," the Financial Accountability and Corporate Transparency (FACT) Coalition pointed out in a press release on Monday.
Ryan Gurule, policy director at the FACT Coalition, said that "this bill cannot be the final chapter in the fight against profit-shifting and offshoring practices by large corporations."
"There is still too much vital revenue on the line," added Gurule, "as tax-dodging multinational corporations are still able to play games with their operational and accounting practices to shift hundreds of billions of dollars in profits each year to secretive tax havens."
Corporate America's relentless year-long lobbying campaign partially paid off this past weekend when Senate Democrats--constrained by two industry-allied lawmakers in their own party and united GOP opposition--approved legislation that stands as a mere shadow of its predecessor, the Build Back Better Act.
Big business is particularly pleased that it was able to fend off Democrats' push to increase the corporate tax rate and impose other levies on the ultra-rich and private equity firms, which exploit glaring loopholes to systematically avoid taxation.
"Tax-dodging multinational corporations are still able to play games with their operational and accounting practices."
Neil Bradley, chief policy officer at the U.S. Chamber of Commerce--the largest and most influential corporate lobbying group in the country--openly expressed relief Monday at the extent to which the Inflation Reduction Act was scaled back compared to the most ambitious version of Build Back Better, a package that would have partially reversed the 2017 GOP tax cuts.
"If 2017's tax reforms were a 10 and Build Back Better was a zero, where is this? I guess I'd say it's a five," Bradly said of the Inflation Reduction Act in an interview with the Financial Times. "It didn't cut taxes; it raised taxes, but it's a lot better than Build Back Better."
The Chamber was one of a number of powerful business groups that lobbied aggressively against Build Back Better and elements of the Inflation Reduction Act, the original version of which included a provision targeting the notorious carried interest loophole as well as a 15% minimum tax on corporations with more than $1 billion in annual profits.
But thanks to a last-minute intervention by Sen. Kyrsten Sinema (D-Ariz.)--a reliable ally of corporate interests--the carried interest proposal was scrapped entirely while the corporate minimum tax was watered down with a carveout for private equity, which helps bankroll the Arizona Democrat's campaigns.
Senate Democrats opted to replace the carried interest provision with a 1% excise tax on stock buybacks, drawing wails of complaint from corporate lobbying organizations including the Chamber.
As the New York Times reported Monday, the proposed corporate minimum tax "had already been whittled down before the changes over the weekend" due to Sinema, who "pushed last week to preserve deductions that manufacturers use to offset the cost of equipment purchases."
Additionally, the Times noted, "lawmakers decided to keep a deduction for wireless spectrum purchases that telecommunications companies said was important for the rollout of high-speed broadband."
The National Association of Manufacturers, a corporate lobbying group that targeted Sinema with a late-stage flurry of ads opposing the minimum tax, voiced appreciation that "the 'book tax' has been revised to reflect the importance of job-creating investments in machinery and equipment."
The organization still expressed opposition to the Inflation Reduction Act as a whole, claiming the "new taxes will still deliver a blow to our industry's ability to raise wages, hire workers, and invest in our communities."
Related Content
While advocates of progressive tax policy largely praised the Inflation Reduction Act as a step in the right direction, they expressed concern that the bill doesn't go nearly far enough to cut off tax dodging by large companies--a critique vindicated by the bill's partly favorable reception in some segments of corporate America.
"Left out of the Inflation Reduction Act were key fixes to the U.S. international tax code that would more definitively remove the incentive for large multinationals to shift profits offshore or erode the U.S. tax base," the Financial Accountability and Corporate Transparency (FACT) Coalition pointed out in a press release on Monday.
Ryan Gurule, policy director at the FACT Coalition, said that "this bill cannot be the final chapter in the fight against profit-shifting and offshoring practices by large corporations."
"There is still too much vital revenue on the line," added Gurule, "as tax-dodging multinational corporations are still able to play games with their operational and accounting practices to shift hundreds of billions of dollars in profits each year to secretive tax havens."