SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
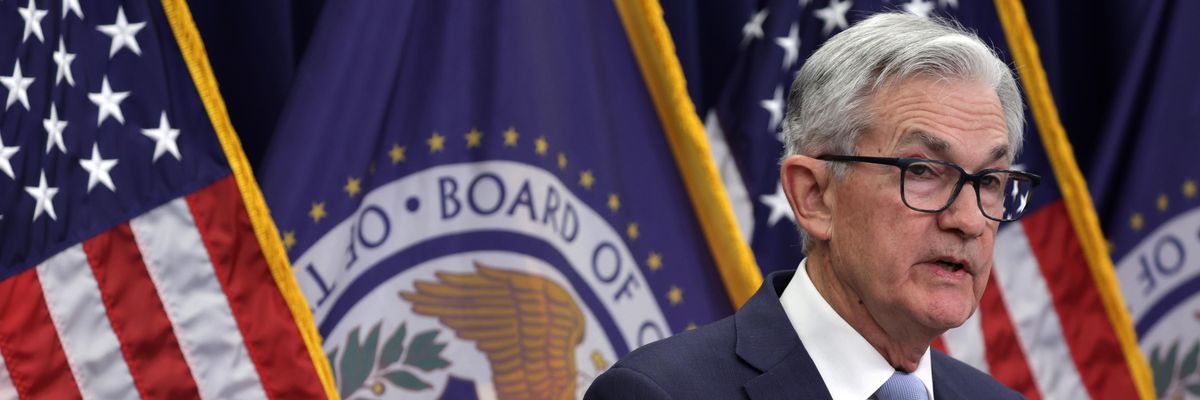
Federal Reserve Chair Jerome Powell speaks at a press conference in Washington, D.C. on December 14, 2022. (Photo: Chip Somodevilla/Getty Images)
The Federal Reserve on Wednesday raised interest rates by half a percentage point and indicated that more hikes are coming in 2023, brushing aside mounting warnings from economists and policy experts that its actions risk hurling the U.S. economy into recession and throwing millions out of work.
The Fed's latest rate increase, less aggressive than the 75-basis-point hikes of the four previous months, pushes interest rates to their highest level in 15 years, a restrictive policy stance explicitly aimed at tamping down economic demand, slowing hiring, and cutting workers' wages even as inflation shows clear signs of cooling significantly.
In a statement, the central bank's Federal Open Market Committee (FOMC) said it "anticipates that ongoing [interest rate] increases in the target range will be appropriate in order to attain a stance of monetary policy that is sufficiently restrictive to return inflation to 2% over time."
The Fed also released its updated economic projections, estimating that gross domestic product (GDP) growth will slow next year and the unemployment rate will rise significantly--a reflection of the impact the central bank's policy moves have had on the U.S. economy thus far.
Liz Zelnick, director of the Economic Security and Corporate Power program at Accountable.US, said in a statement that "recession is not inevitable, but that depends largely on the Fed."
"While the Fed took a step in the right direction by easing off more aggressive rate hikes, it should quit while it's ahead," said Zelnick. "Now is the time for policymakers to focus on what is keeping the economy from soaring--corporate greed. Job-killing interest rate hikes have clearly not deterred corporations from excessively raising prices on working families despite reporting record profits and enriching investors."
During a press conference following the rate hike, Fed Chair Jerome Powell said that while "inflation data received so far for October and November show a welcome reduction in the monthly pace of price increases," he believes it "will take substantially more evidence to give confidence that inflation is on a sustained downward path."
The 50-basis-point rate increase comes as the Fed leadership continues to face growing outside pressure--as well as some concerns from central bank officials--over its aggressive approach to combating inflation, which progressive critics argue is being fueled by outsized corporate profits and supply chain snags, not an overly tight labor market or excessive demand.
"Today's inflation comes mostly from sectoral supply side disruptions, largely the result of the Covid-19 pandemic and its consequent disturbances to supply chains; and disruptions to energy and food markets originating from Russia's invasion of Ukraine," Joseph Stiglitz, a recipient of the Nobel Memorial Prize in Economic Sciences, and Ira Regmi, manager of the Macroeconomic Analysis program at the Roosevelt Institute, wrote in a paper published last week.
"While we welcome the return of interest rates to more normal levels, which reduces a number of distortions associated with persistent, abnormally low interest rates, increasing interest rates too far and too quickly risks a painful slowdown to the economy with minimal benefits to inflation short of a significant downturn," they added. "This would have particular adverse distributional consequences, especially for marginalized groups in the country."
Robert Reich, the former head of the U.S. Department of Labor, noted in response to the Fed's announcement Wednesday that "the real purchasing power of American workers continues to drop" as inflation outpaces wage growth for many workers.
"This is absolutely not the time for more interest rate hikes that make it even harder for working people to keep the lights on," Reich argued.
This story has been updated to include comment from Accountable.US.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
The Federal Reserve on Wednesday raised interest rates by half a percentage point and indicated that more hikes are coming in 2023, brushing aside mounting warnings from economists and policy experts that its actions risk hurling the U.S. economy into recession and throwing millions out of work.
The Fed's latest rate increase, less aggressive than the 75-basis-point hikes of the four previous months, pushes interest rates to their highest level in 15 years, a restrictive policy stance explicitly aimed at tamping down economic demand, slowing hiring, and cutting workers' wages even as inflation shows clear signs of cooling significantly.
In a statement, the central bank's Federal Open Market Committee (FOMC) said it "anticipates that ongoing [interest rate] increases in the target range will be appropriate in order to attain a stance of monetary policy that is sufficiently restrictive to return inflation to 2% over time."
The Fed also released its updated economic projections, estimating that gross domestic product (GDP) growth will slow next year and the unemployment rate will rise significantly--a reflection of the impact the central bank's policy moves have had on the U.S. economy thus far.
Liz Zelnick, director of the Economic Security and Corporate Power program at Accountable.US, said in a statement that "recession is not inevitable, but that depends largely on the Fed."
"While the Fed took a step in the right direction by easing off more aggressive rate hikes, it should quit while it's ahead," said Zelnick. "Now is the time for policymakers to focus on what is keeping the economy from soaring--corporate greed. Job-killing interest rate hikes have clearly not deterred corporations from excessively raising prices on working families despite reporting record profits and enriching investors."
During a press conference following the rate hike, Fed Chair Jerome Powell said that while "inflation data received so far for October and November show a welcome reduction in the monthly pace of price increases," he believes it "will take substantially more evidence to give confidence that inflation is on a sustained downward path."
The 50-basis-point rate increase comes as the Fed leadership continues to face growing outside pressure--as well as some concerns from central bank officials--over its aggressive approach to combating inflation, which progressive critics argue is being fueled by outsized corporate profits and supply chain snags, not an overly tight labor market or excessive demand.
"Today's inflation comes mostly from sectoral supply side disruptions, largely the result of the Covid-19 pandemic and its consequent disturbances to supply chains; and disruptions to energy and food markets originating from Russia's invasion of Ukraine," Joseph Stiglitz, a recipient of the Nobel Memorial Prize in Economic Sciences, and Ira Regmi, manager of the Macroeconomic Analysis program at the Roosevelt Institute, wrote in a paper published last week.
"While we welcome the return of interest rates to more normal levels, which reduces a number of distortions associated with persistent, abnormally low interest rates, increasing interest rates too far and too quickly risks a painful slowdown to the economy with minimal benefits to inflation short of a significant downturn," they added. "This would have particular adverse distributional consequences, especially for marginalized groups in the country."
Robert Reich, the former head of the U.S. Department of Labor, noted in response to the Fed's announcement Wednesday that "the real purchasing power of American workers continues to drop" as inflation outpaces wage growth for many workers.
"This is absolutely not the time for more interest rate hikes that make it even harder for working people to keep the lights on," Reich argued.
This story has been updated to include comment from Accountable.US.
The Federal Reserve on Wednesday raised interest rates by half a percentage point and indicated that more hikes are coming in 2023, brushing aside mounting warnings from economists and policy experts that its actions risk hurling the U.S. economy into recession and throwing millions out of work.
The Fed's latest rate increase, less aggressive than the 75-basis-point hikes of the four previous months, pushes interest rates to their highest level in 15 years, a restrictive policy stance explicitly aimed at tamping down economic demand, slowing hiring, and cutting workers' wages even as inflation shows clear signs of cooling significantly.
In a statement, the central bank's Federal Open Market Committee (FOMC) said it "anticipates that ongoing [interest rate] increases in the target range will be appropriate in order to attain a stance of monetary policy that is sufficiently restrictive to return inflation to 2% over time."
The Fed also released its updated economic projections, estimating that gross domestic product (GDP) growth will slow next year and the unemployment rate will rise significantly--a reflection of the impact the central bank's policy moves have had on the U.S. economy thus far.
Liz Zelnick, director of the Economic Security and Corporate Power program at Accountable.US, said in a statement that "recession is not inevitable, but that depends largely on the Fed."
"While the Fed took a step in the right direction by easing off more aggressive rate hikes, it should quit while it's ahead," said Zelnick. "Now is the time for policymakers to focus on what is keeping the economy from soaring--corporate greed. Job-killing interest rate hikes have clearly not deterred corporations from excessively raising prices on working families despite reporting record profits and enriching investors."
During a press conference following the rate hike, Fed Chair Jerome Powell said that while "inflation data received so far for October and November show a welcome reduction in the monthly pace of price increases," he believes it "will take substantially more evidence to give confidence that inflation is on a sustained downward path."
The 50-basis-point rate increase comes as the Fed leadership continues to face growing outside pressure--as well as some concerns from central bank officials--over its aggressive approach to combating inflation, which progressive critics argue is being fueled by outsized corporate profits and supply chain snags, not an overly tight labor market or excessive demand.
"Today's inflation comes mostly from sectoral supply side disruptions, largely the result of the Covid-19 pandemic and its consequent disturbances to supply chains; and disruptions to energy and food markets originating from Russia's invasion of Ukraine," Joseph Stiglitz, a recipient of the Nobel Memorial Prize in Economic Sciences, and Ira Regmi, manager of the Macroeconomic Analysis program at the Roosevelt Institute, wrote in a paper published last week.
"While we welcome the return of interest rates to more normal levels, which reduces a number of distortions associated with persistent, abnormally low interest rates, increasing interest rates too far and too quickly risks a painful slowdown to the economy with minimal benefits to inflation short of a significant downturn," they added. "This would have particular adverse distributional consequences, especially for marginalized groups in the country."
Robert Reich, the former head of the U.S. Department of Labor, noted in response to the Fed's announcement Wednesday that "the real purchasing power of American workers continues to drop" as inflation outpaces wage growth for many workers.
"This is absolutely not the time for more interest rate hikes that make it even harder for working people to keep the lights on," Reich argued.
This story has been updated to include comment from Accountable.US.